

Blogs
Global Refrigerated Vending Machine Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
From 2020 to 2035, the refrigerated vending machine market is projected to witness robust growth, with total revenue rising from USD 2,350 Million in 2020 to approximately USD 7,980 Million by 2035. This threefold increase is driven by sustained demand for automated retail and technological advancements, encouraging organizations to update and expand vending infrastructure. The influx of smart, IoT-enabled machines and new applications in the healthcare and pharmaceutical sectors contribute to this upward trend. Regionally, the market benefits from increased urbanization, higher consumer spending, and policy support for innovative retail distribution methods. The consistent year-over-year expansion signals strong investor confidence and ongoing innovation within the industry.
Read More - https://bussinessinsights.com/research-report/global-refrigerated-vending-machine
The market in 2025 reveals food and beverages as the primary applications for refrigerated vending machines. These categories benefit from the increasing demand for convenient, fresh, and ready-to-consume options in workplaces, transit stations, and educational institutions. Pharmaceuticals hold a significant position, as temperature-sensitive medications and diagnostic kits drive adoption in healthcare settings. New applications are emerging in retail and transit, enabling operators to tap into broader customer bases and diversify revenue streams. The trend toward healthy and personalized consumer offerings is set to fuel continued growth across diverse segments and amplify the presence of innovative vending solutions.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-refrigerated-vending-machine
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global runway cleaning machine market is on a steady upward trajectory, with annual revenues reflecting continuous growth from 2020 to 2035. Driven by rapid airport infrastructure development, regulatory compliance, and emerging technologies, the market is projected to reach $2,050 Million by 2035, up from $1,080 Million in 2025. Investment acceleration in APAC and MEA, coupled with a strong shift towards automation and green technologies, bolster long-term prospects. This growth signals robust equipment demand among airports, defense sectors, and industrial airfield operators worldwide.
Read More - https://bussinessinsights.com/research-report/global-runway-cleaning-machine
Airport runways remain the dominant application for cleaning machines in 2025, holding a significant share due to the sheer number of airports and frequency of runway operations worldwide. Military airbases, while fewer in number, are critical consumers because of the need for high operational readiness and safety. Usage on helipads, industrial airstrips, and commercial airfields is notable, driven by regulatory compliance and operational safety. As air traffic continues to escalate and new airfields emerge, airport runways will further consolidate their leading role, supported by investments in both new and retrofit projects.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-runway-cleaning-machine
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Smoked Salmon Market Hits $541 Million in 2025, Projects 5.6% CAGR Through 2032
By PW Consulting, 2026-09-16
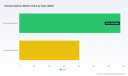
Strategic Horizons: Navigating the Smoked Salmon Market Through 2032
The global smoked salmon industry stands at a critical inflection point. As supply chains mature and consumer preferences shift toward premium protein sources, understanding the trajectory of this market is no longer optional for stakeholders operating at scale. Our latest research publication delivers a comprehensive assessment of the sector, distilling twelve years of historical performance and forward-looking projections into an actionable intelligence framework. For executives planning capital allocation, product development, and geographic expansion in 2026, this report serves as the foundational reference for disciplined decision-making.
The value proposition of this study lies not merely in aggregation, but in synthesis. Where many market assessments stop at headline figures, this analysis traces the structural forces that will define competitive positioning over the next seven years. Readers who approach this document as a strategic compass rather than a static dataset will find a clear pathway through an environment characterized by both robust demand fundamentals and intensifying operational complexity.
Industry Trajectory and Structural Momentum
The market has demonstrated consistent expansion across the historical review window, recovering from mid-cycle fluctuations and establishing a higher baseline entering the forecast horizon. After reaching a valuation of 541.0 million USD in the base year of 2025, the sector moves into a projected growth phase that extends through 2032. The compound annual growth rate of 5.6 percent reflects a measured but durable expansion profile, one that rewards participants capable of balancing volume scale with margin discipline.
This trajectory is underpinned by several interlocking dynamics. Consumer demand continues to favor seafood protein as a cornerstone of modern dietary patterns, while retail and food service channels alike are expanding their premium cold-cut and prepared protein assortments. At the same time, the production ecosystem is responding to supply-side pressures ranging from raw material sourcing constraints to evolving regulatory expectations. The interplay between these demand-pull and supply-push forces creates a landscape where operational readiness, rather than market entry alone, determines which organizations capture disproportionate share.
Our forecast framework extends through 2032, tracing a path from the 587.32 million USD expected in 2026 to a projected 788.0 million USD by the terminal year of the analysis window. The progression is not a simple linear extrapolation; it incorporates the shifting weight of channel consumption, the maturation of regional supply networks, and the cadence of product innovation that will redefine value perception among end consumers. Executives who map their internal planning against this progression will be better positioned to synchronize capacity investments, inventory strategies, and go-to-market timing with the actual pace of market absorption.
Competitive Architecture and Strategic Positioning
The competitive landscape is defined by a concentration profile that rewards scale, brand equity, and channel relationships while leaving room for differentiated specialists to capture premium niches. According to the concentration metrics embedded in our analysis, the top three firms account for approximately 32 percent of the market, and the top five together command roughly 45 percent. This structure indicates a moderately consolidated arena where leading incumbents retain meaningful influence over pricing norms, supplier relationships, and category standards, yet where fragmentation below the top tier allows for opportunistic positioning by agile operators.
Across North America, Europe, and select international nodes, a diverse set of manufacturers is shaping the category. Long-established producers such as Acme Smoked Fish Corporation and Haifa Smoked Fish have built distribution footprints that span retail and foodservice, with private label partnerships and broad cold-smoked portfolios anchoring their relevance to large-scale buyers. Operators like Honey Smoked Fish Co., Boston Smoked Fish Co., and Forman & Field emphasize craftsmanship narratives, leveraging traditional smoking methods, local sourcing, and heritage positioning to command premium price points. Meanwhile, vertically integrated and export-oriented players including Bakkafrost Scotland, Trident Seafoods, and Suempol Sp. z o.o. balance volume production with geographic diversification, supplying fresh and smoked salmon variants across multiple destinations.
Recent corporate activity underscores the competitive intensity. In early 2026, Trident Seafoods expanded its smoked salmon line with a premium King Smoked Salmon offering, signaling a direct push into the higher-value tier. Around the same period, Echo Falls Seafoods, operating under Ocean Beauty Seafoods, unveiled flavor and retail packaging innovations for salmon caviar products at Seafood Expo North America, extending the category footprint beyond whole fillet formats. Natural Grocers entered the retail assortment landscape with a private-label Wild Smoked Salmon line featuring sockeye and coho varieties, certified under the Marine Stewardship Council and cold smoked in small batches at a seaside smokehouse. This launch illustrates how retailer-branded offerings continue to pressure branded manufacturers while also raising the bar for quality signaling and traceability.
Not all developments are expansionary. The category has also been shaped by product integrity events that reinforce the centrality of food safety as a strategic asset. In late 2025, both Haifa Smoked Fish and Acme Smoked Fish issued voluntary recalls related to potential Listeria contamination in cold-smoked products, with one involving a private label assortment tied to a major retailer. These episodes highlight the operational accountability that accompanies cold-smoked production, particularly under the FDA's Fish and Fishery Products Hazards and Controls Guidance, which mandates rigorous sanitation and environmental monitoring for Listeria in cold-smoked environments. For decision-makers, the strategic implication is clear: quality assurance infrastructure, supplier oversight, and rapid response capability are competitive differentiators, not merely compliance functions.
Demand Channels and Product Form Evolution
The consumption architecture of the market is distributed across retail and food service channels, each with distinct purchase drivers, format requirements, and price sensitivity profiles. Retail demand favors branded differentiation, convenient packaging, and clear quality credentials, while food service demand emphasizes consistency, portion control, and menu versatility. Our segmentation analysis examines how these channels interact with product types, revealing where margin opportunities concentrate and where volume-led strategies remain viable.
Within product form, cold-smoked and hot-smoked preparations serve different culinary applications and consumer experiences. Cold-smoked offerings generally align with appetizer, deli, and premium retail formats, where texture, aroma, and presentation are primary purchase drivers. Hot-smoked products, by contrast, often connect with ready-to-eat meal occasions and foodservice menus that prioritize warmth, robustness, and ease of preparation. The balance between these forms shapes production planning, smokehouse utilization, and the product innovation agenda of leading manufacturers.
Smoked Salmon Market
Innovation activity in recent months points to a broader category expansion beyond traditional fillet formats. Flavor experimentation, packaging refinement, and the introduction of derivative products such as salmon caviar indicate that manufacturers are seeking incremental growth through differentiation rather than relying solely on volume gains. Retailers and private label operators are simultaneously curating assortments that emphasize species variety, certification signals, and small-batch production narratives. This dual pressure from branded producers and retailer offerings is reshaping shelf strategy and menu integration across both channels.
Regulatory Environment and Trade Friction
Regulatory and trade conditions form a persistent layer of complexity in the smoked salmon market. U.S. import requirements and permitting regimes apply to many fishery products, including smoked salmon from certain origins, driven by disease and health standard considerations. These restrictions can influence sourcing strategies, lengthen lead times, and create volatility in cross-border supply planning. At a regional level, facility-level export constraints have also been observed, with indications that certain operations may face ongoing limitations on shipments to the United States into the first half of 2026. Such disruptions can cascade through downstream distribution networks, making geographic diversification and multi-origin sourcing strategically valuable.
On the domestic compliance side, the enforcement of the FDA's hazard controls guidance places cold-smoked production under continuous scrutiny for sanitation and environmental monitoring. This regulatory backdrop elevates the importance of validated process controls, supplier verification, and documentation rigor. For organizations evaluating capacity investments or supplier partnerships, the compliance burden is not a peripheral concern but a core determinant of operating risk and brand reputation. Our report integrates these regulatory considerations into the broader market framework, enabling readers to assess where friction is likely to persist and how leading operators adapt their operating models in response.
Strategic Relevance for 2026 Decision-Making
The strategic utility of this research for 2026 planning is rooted in its ability to connect macro momentum with operational reality. Executives facing capital allocation decisions can use the growth trajectory and concentration profile to calibrate expectations around market entry difficulty, share capture potential, and the realistic cadence of revenue scaling. Product and innovation teams can align their roadmaps with the observed direction of channel preferences, species and format diversification, and the certification and quality signals that increasingly influence purchase behavior. Supply chain and procurement leaders can benchmark their sourcing strategies against a backdrop of trade restrictions, multi-origin supply dynamics, and the heightened accountability surrounding cold-smoked safety controls.
This report is designed to support scenario-based thinking. Rather than presenting a single predetermined outcome, it structures the evidence so that leadership teams can test assumptions about pricing power, channel mix, capacity expansion, and geographic prioritization. The analysis examines how concentration dynamics affect competitive response times, how regulatory and trade conditions shape the cost and reliability of supply, and how product innovation cycles influence category perception and consumption frequency. Each of these dimensions is mapped to practical decision points, allowing subscribers to translate intelligence into planning inputs with precision.
In a market where the difference between effective and ineffective strategy often comes down to the quality of early-stage information, this study provides the granularity needed to move beyond broad assumptions. The macro outlook establishes the size and pace of the opportunity; the competitive and operational analysis reveals who is acting, how they are acting, and where the structural pressures are most acute; and the channel and product-form discussion clarifies where value creation is most defensible. Together, these elements form a decision-support foundation that is intended to be referenced repeatedly throughout the planning cycle, not merely read once and filed.
Smoked Meats Market
What This Study Delivers
Our methodology combines historical performance review with a seven-year forecast, anchored in a base year of 2025 and extending through 2032. The study examines total market size progression, growth rate assumptions, and the structural components that drive divergence across regions, product types, and applications. Segmentation is presented with the analytical depth required to understand relative scale and strategic relevance, while preserving the confidentiality of the finer breakdowns that constitute the full intelligence asset.
The competitive section profiles the companies that materially influence supply, pricing, and category direction, integrating recent developments such as new product introductions, private label expansions, packaging and flavor innovations, and product integrity events. These developments are contextualized within broader industry dynamics, including macro import patterns for seafood products, the weight and value share of salmon within those imports, and the specific regulatory requirements that shape production and trade. By weaving together company-level action with sector-level conditions, the report enables readers to interpret discrete events as part of a coherent strategic narrative.
Beyond the published segments, the complete study contains detailed regional and application-level breakdowns, type-specific evolution paths, company profiles with operational context, and scenario-oriented interpretation that supports targeted planning. These components are structured to answer the questions that executive teams repeatedly encounter: where growth is concentrated, which players are positioned to benefit, how regulatory and trade conditions alter the cost of participation, and what product and channel moves are most likely to resonate with demand. The report is therefore both an information resource and a planning instrument, intended for use in budgeting, sourcing strategy, product portfolio review, and competitive benchmarking.
Conclusion: Positioning for Durable Advantage
The smoked salmon market in 2026 is neither a nascent category nor a mature commodity play. It is a differentiated protein segment with steady growth characteristics, meaningful concentration among leading operators, and a competitive environment that increasingly rewards quality signaling, channel readiness, and operational discipline. The organizations that navigate the next phase most effectively will be those that treat intelligence as a strategic input rather than a retrospective summary.
This research publication has been designed to support that approach. It provides the scale and trajectory needed to frame opportunity, the competitive and regulatory context needed to manage risk, and the segmentation depth needed to prioritize action. For leaders shaping 2026 strategy, the value lies in using the analysis to pressure-test assumptions, align cross-functional plans, and identify the specific moves that convert market momentum into durable advantage. The full report extends far beyond the outline presented here, offering the complete dataset, company-by-company detail, and interpretive guidance necessary to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Smoked Salmon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global revenue for drone robots demonstrates robust growth, climbing from $5,600 million in 2020 to an expected $23,150 million by 2035, propelled by rapid innovation and broadening industry use. Yields are notably accelerating post-2025 with the integration of AI, expanded commercial regulations, and increasing consumer demand. The period from 2025 to 2030 marks a compound annual growth rate exceeding 15%, attributed to rising sales in logistics, agriculture, and defense, especially in the Asia-Pacific and North American regions.
Read More - https://bussinessinsights.com/research-report/global-drone-robots
The applications landscape in the drone robots market reveals that defense and surveillance account for the largest market share due to sustained government procurement and security investments. Agriculture follows, leveraging drones for crop assessment and yield optimization, while logistics and delivery gain ground driven by rising e-commerce activity. Mapping, media, and entertainment applications reflect increasing consumer and enterprise adoption for aerial photography, broadcasting, and terrain analysis. Defense and agriculture continue to set the pace for overall market expansion in 2025.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-drone-robots
Frequently Asked Questions
Who are the key players in Global Drone Robots industry?
The top five players in the global drone robots industry are DJI, Parrot SA, AeroVironment Inc., Northrop Grumman, and SZ DJI Technology Co., Ltd. These companies are recognized for their technological innovation, extensive product portfolios, and strong market presence across various commercial, military, and industrial drone segments.
What is the Global Drone Robots growth?
The global drone robots market has witnessed significant growth, driven by increasing commercial adoption and government investments. In 2023, DJI reported rising sales due to heightened demand in agriculture and surveying, demonstrating the accelerated industry growth and expanding application areas.
Which segment accounted for the largest Global Drone Robots share?
The commercial applications segment, particularly in agriculture, surveillance, and delivery, accounted for the largest market share in global drone robots. Drone usage in precision farming, promoted by companies like DJI and Parrot, fuels this wide segment adoption, helping optimize crop yields and operational efficiency.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Medical Ultrasonic Cleaners Market to Hit $1.98B by 2032, 6.8% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Medical Ultrasonic Cleaners Market 2026-2032: A Executive Outlook
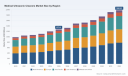
The global medical ultrasonic cleaners market stands at a critical inflection point as healthcare infrastructure modernization, stringent infection control mandates, and evolving regulatory frameworks reshape equipment procurement cycles. Over the 2026–2032 forecast horizon, the sector is projected to advance at a compound annual growth rate of 6.8 percent, translating into a trajectory from 1331.54 million USD in 2026 to 1980.92 million USD by 2032. This sustained expansion is not merely a function of volume replacement; it reflects a structural revaluation of decontamination workflows within sterile processing departments, operating rooms, and centralized instrument reprocessing facilities. For executives navigating medical device manufacturing, healthcare operations, or sterile supply chain management, the current market phase demands more than incremental procurement adjustments. It requires a disciplined, data-informed approach to technology adoption, regional deployment, and competitive positioning. Our newly released Medical Ultrasonic Cleaners Market research delivers precisely that analytical infrastructure, translating macro momentum into actionable enterprise strategy.
Market Trajectory and the 2026 Investment Thesis
Growth in the ultrasonic cleaning sector has accelerated decisively since 2020, when the market was valued at 987.65 million USD. By 2025, revenue had climbed to 1273.5 million USD, reflecting a compound expansion of roughly 6 percent annually across the historical record. The forecast period extends this momentum, with revenue projected to cross 1524.59 million USD in 2028, 1751.76 million USD in 2030, and 1913.12 million USD in 2031, before stabilizing at 1980.92 million USD in 2032. This trajectory is underpinned by three converging forces: the replacement of legacy manual decontamination protocols, the integration of ultrasonic technology into automated reprocessing lines, and the growing recognition of ultrasonic cavitation as a repeatable, validated method for contaminant removal on complex surgical and dental instrument geometries.
Medical Desktop Ultrasonic Equipment Market
For 2026 strategic planning, the most salient implication is that volume growth is increasingly tied to capability upgrades rather than baseline installation counts. Healthcare networks are reassessing capital expenditure priorities in light of labor constraints, throughput bottlenecks, and compliance documentation requirements. Ultrasonic systems that deliver programmable cycles, reproducible rinse profiles, and digital validation outputs are transitioning from optional enhancements to operational necessities. The research emphasizes that organizations which anchor their 2026 procurement roadmaps to process standardization, instrument throughput targets, and total cost of ownership modeling will capture disproportionate efficiency gains relative to peers pursuing ad hoc equipment rotation.
Core Report Architecture: From Data Layers to Decision Frameworks
The study is structured to support multi-functional decision-making across procurement, clinical operations, regulatory affairs, and market development. Rather than presenting isolated statistics, the analysis integrates demand-side drivers, supply-side capacity signals, and operational benchmarks into a cohesive planning environment. Key analytical modules include:
- Demand driver mapping across surgical, dental, laboratory, and medical device reprocessing workflows, with emphasis on throughput requirements, cycle validation expectations, and decontamination chain integration points.
- Product configuration analysis that distinguishes between benchtop, industrial, and specialized formats, linking tank capacity, frequency stability, and control architecture to use-case suitability and procurement risk.
- Regional deployment intelligence that evaluates healthcare spending patterns, manufacturing footprint expansion, and localized compliance expectations across major economic corridors without isolating granular share percentages.
- Competitive benchmarking that profiles product positioning, recent commercial moves, and strategic intent across the leading participants shaping category standards.
- Scenario-based modeling that allows leadership teams to test procurement timing, capacity expansion, and partnership strategies against shifting regulatory and reimbursement conditions.
This architecture is designed for execution. Procurement leaders can calibrate specification thresholds against validated deployment patterns. Clinical operations teams can align decontamination workflows with cycle reproducibility and purity expectations. Commercial teams can identify account segments where digital control upgrades, modular reconfiguration, or eco-friendly agent compatibility directly influence purchasing velocity. The report deliberately refrains from over-disclosing sub-segment percentages and localized valuation breakdowns within this executive preview; those layers remain fully accessible in the complete intelligence package, where the granularity supports precise territory planning and product-mix optimization.
Competitive Architecture and Strategic Orbital Moves
The competitive field is moderately concentrated, with the top three firms accounting for approximately 28.5 percent of category revenue and the top five expanding that footprint to roughly 35.2 percent. This concentration signals a market where scale, application specialization, and compliance readiness increasingly separate leaders from followers. Several manufacturers have moved aggressively to reinforce their positions through targeted product evolution, partnership formation, and regulatory alignment.
Crest Ultrasonics, headquartered in Trenton, New Jersey, has sharpened its focus on precision cleaning for surgical and medical instruments through healthcare-oriented product lines such as the Healthcare Pro Junior series, which incorporates multi-cycle wash and rinse capabilities alongside digital controls tailored for sterile processing environments. In September 2025, the company entered a strategic partnership with a leading hospital network to deliver customized ultrasonic cleaning solutions, a move that underscores the growing preference for networked deployments aligned to institutional workflow specifications.
Elma Schmidbauer GmbH, based in Singen, Germany, continues to advance modular ultrasonic cleaning platforms and has introduced eco-friendly InnoWave PCF models designed to support medical device instrument reprocessing and decontamination under evolving medical device regulation expectations. In July 2025, the company unveiled an eco-friendly ultrasonic cleaner utilizing biodegradable cleaning agents for medical applications, highlighting an industry-wide shift toward agent compatibility, waste stream management, and environmental compliance within sterile decontamination processes. Regulatory documentation reinforces that Elma Schmidbauer medical ultrasonic cleaners are positioned for instrument reprocessing in medical technology applications, with ultrasound cleaning systems expected to provide reproducible processes and the highest purity standards in medical device manufacturing.
Branson Ultrasonics, operating from Danbury, Connecticut, has reinforced its emphasis on digital control sophistication for surgical instrument cleaning. In August 2025, the company announced a new line of ultrasonic cleaners specifically for surgical instruments, incorporating advanced digital controls intended to enhance cleaning efficiency and support validation workflows. This product direction aligns with broader operating-room and sterile processing priorities around cycle repeatability, documentation readiness, and reduced manual intervention.
Ultrasonic Power Corporation, based in New Britain, Connecticut, manufactures industrial and medical-grade ultrasonic cleaners for pharmaceutical and medical applications, including custom systems engineered for precision part cleaning. Ultrasonic LLC, also United States-based, supplies machines designed for medical parts cleaning, handling small batches and complex components across healthcare and aerospace-related requirements. Together, these participants reflect a diversifying supplier base in which application specificity, custom configuration capability, and regulatory awareness increasingly influence purchasing decisions.
For enterprise strategists, these competitive signals carry clear implications. Supplier selection is no longer a function of unit price alone; it incorporates validation readiness, cycle programmability, compliance support, and compatibility with institutional decontamination chains. Organizations that evaluate vendors through a multi-criteria scorecard encompassing traceability, digital output quality, service response, and upgrade pathways will be better positioned to lock in operational resilience as category standards tighten.
Operational, Regulatory, and Labor Economics Shaping Procurement Behavior
Beyond competitive dynamics, the market is being reshaped by operational realities that directly influence specification priorities. High-capacity stainless steel tank models in the 5-liter to 8-liter range have become standard in medical ultrasonic cleaners for instrument pre-cleaning, reflecting a broader shift toward throughput-compatible hardware that can process reusable instrument sets efficiently at the front end of decontamination workflows. This hardware normalization reduces variability in cycle execution while supporting consistent exposure of instrument surfaces to cavitation activity.
Labor economics are also accelerating adoption. Ultrasonic cleaners deliver measurable labor savings by replacing manual cleaning methods for surgical instruments in sterile processing departments. As staffing pressures persist and training consistency becomes a recognized operational risk, automated or semi-automated cleaning cycles offer a practical lever for reducing variability, reducing rework, and improving instrument readiness before sterilization. Reimbursement and compliance structures further reinforce this direction. In practice, instrument cleaning equipment used in healthcare settings must support decontamination prior to autoclaving, and systems that align with established healthcare standards are increasingly favored during procurement reviews and quality audits.
Regulatory context adds another layer of strategic relevance. Medical technology applications are subject to evolving expectations around documentation, process reproducibility, and validation traceability. Organizations are therefore placing greater weight on equipment that supports repeatable cycles, verifiable rinse outcomes, and integration into broader quality management systems. In this environment, procurement decisions are increasingly evaluated not just on cleaning performance in isolation, but on how effectively a system supports downstream compliance and sterilization readiness.
Medical Ultrasonic Cleaners Market
Strategic Playbook for 2026 Enterprise Decision-Makers
Translating these dynamics into executable strategy requires a structured approach. The research outlines several priorities that resonate across healthcare networks, medical device manufacturers, and equipment distributors:
- Define instrument reprocessing targets first, then map equipment specifications to those targets. Throughput, cycle flexibility, and validation output should be treated as interdependent decision variables rather than separate purchasing dimensions.
- Embed total cost of ownership analysis into capital planning. Upfront pricing comparisons should be supplemented with assessments of labor displacement, rework reduction, maintenance expectations, and compliance documentation value.
- Align supplier evaluation with future regulatory and environmental expectations. Preference should be given to platforms that accommodate standardized cycle programs, digital record generation, and compatibility with evolving cleaning agent requirements.
- Treat regional deployment as a strategic variable. Healthcare infrastructure maturity, manufacturing presence, and localized service capacity influence implementation timelines and long-term support reliability, making geography a relevant component of procurement planning.
- Use competitive intelligence to anticipate category direction. Recent product launches, partnerships, and eco-friendly innovations signal where specification expectations are heading, enabling earlier internal alignment and reduced procurement friction.
These priorities are not generic best practices; they are derived from the observed intersection of demand-side operational pressures, supplier innovation cadence, and regulatory reinforcement within the ultrasonic cleaning category. Organizations that operationalize them early in the 2026 planning cycle will have a clearer path to procurement efficiency, reduced implementation risk, and stronger alignment with downstream sterilization and quality requirements.
The Complete Intelligence Layer: What Is Held Back and Why
This executive overview is intentionally structured as a strategic preview. The purpose is to establish analytical credibility, demonstrate sector fluency, and clarify how the full report supports decision-making without dispersing the most granular intelligence across public-facing formats. Core segmentation values, regional revenue distributions, application-level breakdowns, and product-type splits remain embedded in the complete study, where they can be cross-referenced against operational benchmarks, competitive profiles, and scenario models without dilution. That architecture allows procurement and strategy teams to apply precise figures to territory planning, product-mix evaluation, and vendor comparison without exposing sensitive analytical layers prematurely.
In practice, the full report provides the quantitative scaffolding required to convert directional momentum into specific procurement, expansion, and partnership decisions. The macro trajectory, competitive positioning, regulatory context, and operational drivers presented here form the strategic foundation; the detailed segmentation and valuation layers supply the execution-level precision. Together, they create a planning environment that supports both short-term purchasing calibration and multi-year capability roadmapping.
Closing Perspective: Positioning for Measured, High-Value Growth
The medical ultrasonic cleaners market is advancing along a clearly defined growth path, but the strategic opportunity lies less in the headline numbers than in the operational and regulatory conditions that are reshaping procurement logic. As the category moves from 1331.54 million USD in 2026 toward nearly 1980.92 million USD in 2032, the organizations that win will be those that convert that momentum into disciplined specification choices, validated workflow integration, and supplier relationships aligned with compliance, reproducibility, and efficiency goals. The complete Medical Ultrasonic Cleaners Market research is built to support precisely that outcome, offering the depth, structure, and benchmarking context required to move from informed awareness to decisive execution.
For detailed analysis of this topic, please visit the official page: Medical Ultrasonic Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global digital drilling rigs market revenue is forecasted to exhibit a strong growth trajectory from 2020 through 2035. Starting at approximately USD 2,195 Million in 2020, the market is projected to reach USD 6,745 Million in 2025 and surge further to USD 21,480 Million by 2035. This upward momentum is fueled by rapid digitalization in drilling operations, regulatory support for automation, and a surge in demand for efficient, low-cost drilling solutions. The year-on-year growth is anticipated to accelerate as advancements in AI, cloud, and IoT become standard across the energy value chain.
Read More - https://bussinessinsights.com/research-report/global-digital-drilling-rigs
Oil & gas exploration remains the primary application for digital drilling rigs, capturing an estimated 57% market share in 2025. The adoption of advanced technologies is notably high for energy production, followed by mining and geothermal sectors—driven by increased demand for sustainable operations and resource management. Growing emphasis on environmental and water well drilling, along with construction applications, is progressively diversifying the usage of digital rigs. The continuous shift toward data-centric, real-time drilling operations underpins these trends.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-digital-drilling-rigs
Frequently Asked Questions
Who are the key players in Global Digital Drilling Rigs industry?
The top five players in the Global Digital Drilling Rigs industry include Schlumberger, Halliburton, Baker Hughes, National Oilwell Varco, and Nabors Industries. These leading companies are pioneers in digital drilling technologies, offering advanced automation, cloud analytics, and real-time monitoring solutions to enhance drilling efficiency and productivity.
What is the Global Digital Drilling Rigs growth?
The Global Digital Drilling Rigs market has experienced significant growth, with a notable surge in digital adoption post-2022. For example, Schlumberger reported robust gains by deploying digital drilling solutions that improve uptime and reduce operational costs, fueling industry-wide growth and accelerating the adoption of digital technologies.
Which segment accounted for the largest Global Digital Drilling Rigs share?
The onshore drilling segment held the largest market share in the Global Digital Drilling Rigs industry. This dominance is driven by increased shale exploration activities, especially in North America, and the enhanced need for digital solutions to optimize operations and ensure better safety and performance in onshore environments.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Embedded Vibration Monitoring System Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global embedded vibration monitoring system market is expected to grow from $1,850 million in 2020 to over $5,320 million by 2035. The market exhibits a healthy compound annual growth rate as industry digitalization and preventive maintenance strategies become standard operating procedures. Early adoption in North America and Europe is gradually being eclipsed by robust expansion in APAC and emerging markets, reflecting a universal transition towards smart maintenance solutions.
Read More - https://bussinessinsights.com/research-report/global-embedded-vibration-monitoring-system
The industrial segment represents the largest application area for embedded vibration monitoring systems in 2025, as manufacturing plants increasingly rely on predictive analytics to ensure operational efficiency. The automotive and energy & power sectors also account for substantial market shares, driven by the need for continuous equipment monitoring and compliance with safety standards. Oil & gas applications remain strong, while aerospace and other segments reflect ongoing but comparatively slower adoption due to stringent regulatory requirements.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-embedded-vibration-monitoring-system
Frequently Asked Questions
Who are the key players in Global Embedded Vibration Monitoring System industry?
Key players include SKF Group, General Electric, Honeywell International Inc., Emerson Electric Co., and Rockwell Automation. These companies are at the forefront of the industry, providing advanced vibration monitoring solutions that enhance industrial safety, efficiency, and predictive maintenance in various manufacturing, energy, and transportation sectors worldwide.
What is the Global Embedded Vibration Monitoring System growth?
The market has experienced robust growth, driven by increased adoption of Industry 4.0 and IoT technologies. For instance, Emerson Electric Co. reported growing deployments across manufacturing plants in 2023, fueled by demand for predictive maintenance tools that reduce downtime and enhance operational efficiency.
Which segment accounted for the largest Global Embedded Vibration Monitoring System share?
The manufacturing segment accounted for the largest market share, with widespread adoption in automotive, power generation, and oil & gas industries. Applications in these sectors focus on equipment health monitoring and early fault detection, leading to reduced maintenance costs and improved equipment longevity.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Coding Equipment Market Hits $6.75B in 2025, Projects CAGR of 6.12% to $10.27B by 2032
By PW Consulting, 2026-09-16
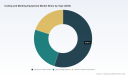
Strategic Imperatives in the Global Coding and Marking Equipment Market: Navigating Growth Through 2032
In an era where supply chain transparency, regulatory compliance, and packaging sustainability dictate competitive advantage, the coding and marking equipment market stands at a critical inflection point. Manufacturing leaders, procurement directors, and automation strategists are no longer asking whether to upgrade their marking infrastructure, but how to align capital allocation with a market that is expanding at a steady pace while simultaneously fragmenting under technological, regulatory, and material-cost pressures. Our latest comprehensive study on the Coding and Marking Equipment Market transforms raw trajectory data into a decision-ready framework, offering executives a clear line of sight into the operational and financial implications of the 2026–2032 forecast window.
The market’s historical foundation provides essential context for forward-looking strategy. Between 2020 and 2025, sector revenue climbed from approximately 5.0 billion USD to 6.75 billion USD, reflecting a period of accelerated line automation, heightened traceability mandates, and widespread adoption of advanced coding technologies across high-volume production environments. This momentum is projected to sustain itself through the end of the decade, with market valuation expected to reach 7.21 billion USD in 2026 and continue its upward trajectory toward 10.27 billion USD by 2032. The forecast period compound annual growth rate of 6.12 percent underscores a mature but structurally resilient industry, one whose expansion is increasingly driven not by volume alone, but by precision, compliance readiness, and lifecycle optimization.
For enterprise decision-makers, these figures represent more than a top-line growth narrative. They signal a shifting capital allocation landscape where legacy equipment refresh cycles, cross-platform compatibility, and total cost of ownership calculations must be recalibrated against a backdrop of evolving packaging substrates, tightening food-safety disclosures, and intensifying competitive consolidation. Our report translates these macro trends into actionable intelligence, enabling strategy teams to stress-test investment theses, benchmark regional performance vectors, and anticipate demand inflection points before they materialize in procurement cycles.
Decoding the Operational Architecture of the Analysis
The study is engineered for practitioners rather than passive observers. It maps the full lifecycle of coding and marking deployment, from technology selection and line integration to maintenance economics and compliance verification. Readers will encounter a methodical dissection of how different printing modalities interact with production throughput, substrate variability, and regulatory labeling requirements. The analysis places particular emphasis on the operational tradeoffs that procurement and engineering teams face daily: balancing ink-based continuity against laser permanence, evaluating thermal transfer durability under abrasive or temperature-fluctuating conditions, and aligning printer head lifecycle with line-speed targets and changeover frequency.
Beyond equipment taxonomy, the report integrates upstream cost dynamics that directly influence capital expenditure planning. Recent shifts in raw material pricing have compressed margins across packaging supply chains, creating ripple effects for coding system operators who must now weigh upfront hardware investments against ongoing consumables volatility. The analysis incorporates these material-cost pressures into scenario modeling, helping executives evaluate whether modular upgrades, ink-substitution strategies, or full-line conversions offer the most defensible path to sustained ROI. This practical orientation ensures that financial teams can align operational roadmaps with realistic cost curves rather than static vendor quotes.
Compliance architecture forms another critical pillar of the study. As labeling requirements become more granular and audit expectations more stringent, the functional scope of coding equipment has expanded beyond simple identifier placement. The report examines how verification workflows, third-party audit readiness, and automated inspection integration are reshaping procurement priorities. Organizations seeking to future-proof their packaging lines will find structured guidance on aligning coding capabilities with traceability mandates, nutrient-disclosure frameworks, and sustainability-driven substrate transitions.
Competitive Dynamics and Strategic Differentiation
The market’s competitive architecture reflects both entrenched 리더십을 and continuous technological repositioning. The sector remains moderately concentrated, with the top three players collectively commanding roughly 45.8 percent of revenue and the top five firms controlling approximately 61.2 percent. This distribution indicates a landscape where scale advantages, service networks, and cross-vertical application expertise create meaningful barriers, yet leave sufficient headroom for specialized innovators and regional specialists to capture value through niche performance differentiation.
At the center of the competitive field are organizations that have built deep application fluency across high-demand verticals. Domino Printing Sciences, headquartered in Cambridge, United Kingdom, has maintained a strong focus on continuous inkjet, laser, and hybrid inkjet coding systems, with dedicated solutions engineered for high-speed traceability on cans, bottles, cartons, and cases. Its recent product cadence illustrates the pace of innovation shaping the market: in March 2026, the company introduced the Cx150i direct-to-box printer utilizing oil-based ink for more sustainable and accessible coding on food packaging, alongside the Ux360i UV Laser Coder designed for high-speed sustainable packaging applications in food and beverage lines. The same period saw the release of the Gx-Series PRO Printhead, built to support the industry’s transition toward 2D coding on food packaging. These developments were preceded by the October 2025 introduction of the Dx1060i CO2 Laser Coder and F-Series fibre lasers, which target permanent code generation on beverage cans, glass, and plastics.
Videojet Technologies, based in Auckland, New Zealand, continues to position its CIJ, TIJ, and laser coder portfolio around permanent, food-safe prints tailored for food and beverage packaging lines. Markem-Imaje, operating from Aubervilliers, France, offers thermal inkjet, continuous inkjet, and laser marking systems calibrated for product- and case-level coding within food and beverage environments. Matthews International Corporation, headquartered in Pittsburgh, Pennsylvania, supplies TIJ, laser, and labeling systems aimed at high-resolution and permanent coding applications, while ID Technology, based in Minneapolis, Minnesota, delivers thermal inkjet coders and integrated systems for direct marking on cans, jugs, and cartons.
The competitive field also includes significant contributions from industrial equipment manufacturers and compliance-adjacent service providers. Hitachi Industrial Equipment Systems, headquartered in Tokyo, Japan, manufactures laser and inkjet coding systems optimized for traceability in industrial food and beverage settings. SATO Holdings Corporation, also based in Tokyo, provides TIJ and thermal transfer coders focused on packaging identification and regulatory compliance. SGS, headquartered in Geneva, Switzerland, extends the ecosystem through third-party verification and audit services for coding and marking systems deployed in food and beverage packaging lines. Rounding out the roster, Gem Gravure, based in the United States, supplies regulation-quality coding equipment specifically engineered for food and beverage packaging applications.
For strategy teams, this competitive mosaic matters because vendor selection is no longer a straightforward equipment-procurement exercise. It is a multi-year partnership decision that encompasses service responsiveness, technology roadmaps, consumables availability, and compliance-support capabilities. The report provides a structured comparison framework that helps organizations evaluate not just hardware specifications, but the broader value chain resilience each supplier brings to high-volume, high-compliance production environments.
Regulatory and Material-Cost Pressures Redefining Market Dynamics
External forces are accelerating the strategic relevance of coding and marking infrastructure. Regulatory evolution is one of the most immediate drivers. In January 2025, the FDA proposed a rule requiring a front-of-package Nutrition Info box on most packaged foods, mandating clear display of saturated fat, sodium, and added sugars categorized as Low, Medium, or High. By April 2025, the agency finalized updates to the healthy nutrient content claim definition, tightening limits on added sugars, saturated fat, and sodium. These developments do not merely change label content; they reshape the precision, legibility, and verification demands placed on coding systems, particularly on high-speed lines where print quality, placement consistency, and audit-ready documentation must remain uncompromised.
Simultaneously, raw material dynamics are injecting cost volatility into packaging production and, by extension, into coding system planning. In 2026, PET, PP, and PS plastic sheet prices rose 15–30 percent due to energy costs and paraxylene supply constraints. Corrugated paperboard and paper packaging costs also increased amid higher pulp and energy prices for food packaging production. For coding and marking operators, these shifts affect substrate compatibility, ink adhesion performance, laser interaction with treated surfaces, and overall line-tuning requirements. Equipment that performs reliably on stable substrate profiles may require recalibration, consumables substitution, or complementary inspection modules when material characteristics fluctuate.
These intersecting pressures are reshaping market dynamics in ways that reward proactive planning. Organizations that treat coding infrastructure as a static cost center risk encountering deployment bottlenecks when regulatory label formats change or when substrate transitions alter print stability. Conversely, enterprises that align their equipment strategy with anticipated regulatory timelines and material-cost trajectories can convert compliance and packaging shifts into efficiency gains, reducing downtime, minimizing rework, and improving audit outcomes.
Why This Study Matters for 2026 Decision-Making
The value of this research lies in its translation of trajectory data into operational clarity. Enterprise leaders operating in 2026 must navigate a market that is simultaneously expanding, consolidating, and being reshaped by compliance mandates and input-cost volatility. Top-line growth figures alone cannot guide capital deployment; they must be paired with segmentation intelligence, competitive capability mapping, regulatory horizon scanning, and total-cost modeling that reflects real-world line conditions.
Coding and Marking Equipment Market
Our report delivers that integrated view. It helps strategy and operations teams identify where demand concentration is forming, which technology pathways align with upcoming packaging and labeling requirements, and how vendor portfolios differ in their capacity to support rapid changeover, substrate variability, and verification workflows. It also contextualizes market concentration dynamics, enabling organizations to evaluate whether partnership with a large-scale incumbent, a specialized technology provider, or a service-oriented verification partner best matches their risk tolerance and growth targets.
Crucially, the study is designed to support decisions that extend beyond the current fiscal year. With a forecast horizon stretching to 2032, executives gain a structured basis for multi-phase investment planning, technology refresh scheduling, and capacity alignment. Rather than reacting to equipment obsolescence or compliance gaps after they emerge, organizations can sequence upgrades, model consumables exposure, and stress-test vendor commitments against plausible regulatory and material-cost scenarios.
Accessing the Full Strategic Blueprint
The coding and marking equipment market is entering a phase where precision, compliance, and cost resilience will separate scalable operators from those burdened by reactive procurement. This study provides the analytical foundation needed to navigate that phase with confidence. It combines market trajectory mapping, technology and application segmentation, competitive profiling, and dynamic cost-and-regulation context into a single decision-support instrument.
Coding and Marking Systems and Solutions Market
To explore the complete segmentation breakdown, detailed vendor capability comparisons, scenario-based cost modeling, and region-specific growth vectors, we invite you to access the full report through our source page. The complete intelligence package is structured for immediate integration into capital planning, procurement strategy, and operational roadmapping, enabling your team to move from market awareness to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Coding and Marking Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global bar loader market is projected to grow from USD 845 Million in 2020 to USD 1,390 Million by 2035. This upward trajectory is attributed to increasing industrial automation, expansion in manufacturing sectors, and adoption of advanced bar loader technologies. Year-over-year growth remains steady due to consistent demand from automotive, aerospace, and medical device manufacturers. Investments in smart factory solutions and Industry 4.0 integration further accelerate revenue generation. The marked rise in 2025 is closely linked to post-pandemic industrial revitalization, with revenue gains sustained well into the next decade.
Read More - https://bussinessinsights.com/research-report/global-bar-loader
The automotive industry remains the largest consumer of bar loaders, accounting for over one-third of market share in 2025, driven by demand for precision engineering and automation in mass production. Aerospace and general manufacturing follow closely, reflecting the importance of efficient, repeatable machining in these sectors. The medical industry’s adoption is rising due to stringent precision requirements, while construction and other industries primarily employ bar loaders for specialized mechanical components. As advanced automation spreads, the application landscape of bar loaders is expected to further diversify across industry verticals.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-bar-loader
Frequently Asked Questions
Who are the key players in Global Bar Loader industry?
The leading players in the Global Bar Loader industry include LNS Group, FMB Maschinenbau, IEMCA (Bucci Industries), Edge Technologies, and Haas Automation Inc. These companies drive innovation, offer a comprehensive range of bar feeders/loaders, and have a strong presence globally with robust distribution and after-sales networks.
What is the Global Bar Loader growth?
The Global Bar Loader market has experienced steady growth, with a CAGR of around 4% in recent years, driven primarily by increased adoption in automotive and precision engineering sectors. For instance, IEMCA reported increased sales in Asia-Pacific in 2023, signaling expanding demand for automation solutions.
Which segment accounted for the largest Global Bar Loader share?
The automotive manufacturing application segment accounted for the largest share of the Global Bar Loader market. Bar loaders are widely used in the automotive sector for high-speed, efficient, and automated machining of components, supported by leading OEMs striving for improved productivity and reduced labor costs.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global mower conditioners market is projected to witness steady growth between 2020 and 2035. Revenue figures show a consistent upward trajectory spurred by technological advances, increased mechanization, and a growing customer base worldwide. Between 2025 and 2030, the adoption rate accelerates among medium and large-scale farming enterprises, driving notable jumps in annual revenue, which surpasses $2.6 billion by 2035. Emerging markets in Asia-Pacific and Latin America are expected to play pivotal roles in sustaining this growth, supported by favorable government policies and increasing awareness about the benefits of modern forage equipment.
Read More - https://bussinessinsights.com/research-report/global-mower-conditioners
The agriculture application segment secures the largest share in the mower conditioners market for 2025, representing the principal use case for these machines due to the need for efficient forage crop management. Landscaping follows, reflecting growing urbanization and demand for professionally maintained green spaces across cities. Sports and recreation also register notable share, driven by investments in high-quality turf for golf courses and parks. These trends are buoyed by governments and commercial clients prioritizing sustainability and aesthetic upgrades, spurring increased adoption across non-agricultural sectors. Vendors are responding by diversifying their offerings to meet specialized requirements in each segment, further fueling market expansion.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mower-conditioners
Frequently Asked Questions
Who are the key players in Global Mower Conditioners industry?
The key players in the Global Mower Conditioners industry include John Deere, AGCO Corporation, Kuhn Group, Kubota Corporation, and New Holland (CNH Industrial). These companies excel in producing innovative agricultural machinery, offer robust dealer networks, and continuously invest in R&D to enhance performance, reliability, and efficiency in mower conditioners.
What is the Global Mower Conditioners growth?
The Global Mower Conditioners market is witnessing steady growth, driven by rising demand for efficient forage processing. Recent product launches, such as John Deere’s 2023 expanded model lineup, and technological advancements in automation and precision farming equipment, are fueling adoption in developed and emerging markets alike.
Which segment accounted for the largest Global Mower Conditioners share?
The largest share of the Global Mower Conditioners market is held by agriculture and forage applications. These applications require reliable and high-efficiency grass cutting and conditioning for optimal silage and hay production, prompting farmers to invest significantly in advanced mower conditioners.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com